Anthropic's public S-1 registration statement, the document a company files before selling shares to the public, contains one number that reframes the debate over how much money frontier AI labs burn. In 2023, the company's spending on compute and infrastructure came to 1056 percent of its revenue, roughly $10 of hardware and cloud cost for every $1 earned. By the first half of 2026, that figure had fallen to 55 percent. The head of private companies at Baillie Gifford, an Edinburgh-based investment firm that first backed Anthropic in 2025 and joined its Series G and Series H funding rounds, attributes the shift to a deliberate hardware strategy and to Claude's growing role in making its own training and serving more efficient. He also argues that the governance structure some investors find unusual, a Public Benefit Corporation with founders holding 50.1 percent of voting power, is precisely what a frontier lab needs to keep from trading safety for quarterly results.
The compute curve in four data points
Figures derived from the filing show a steady compression of compute cost relative to revenue over three and a half years:
| Period | Compute and infrastructure spend as a share of revenue |
|---|---|
| 2023 | 1056% |
| 2024 | 653% |
| 2025 | 160% |
| First half of 2026 | 55% |
The trajectory matters because the compression came against top-line growth: revenue rose while compute spend shrank as a share of it. The Baillie Gifford executive says the filing held few surprises for the firm, and that this is by design. The point of investing early in private companies, as he frames it, is to know the business well enough that an S-1 confirms what the investor already believed. If a public filing revealed something entirely new about operations, it would suggest the investment team had not been watching closely enough. In Anthropic's case, the document reinforced a thesis of consistent execution across both engineering and the commercial business.
Why running on four kinds of chips lowers the bill
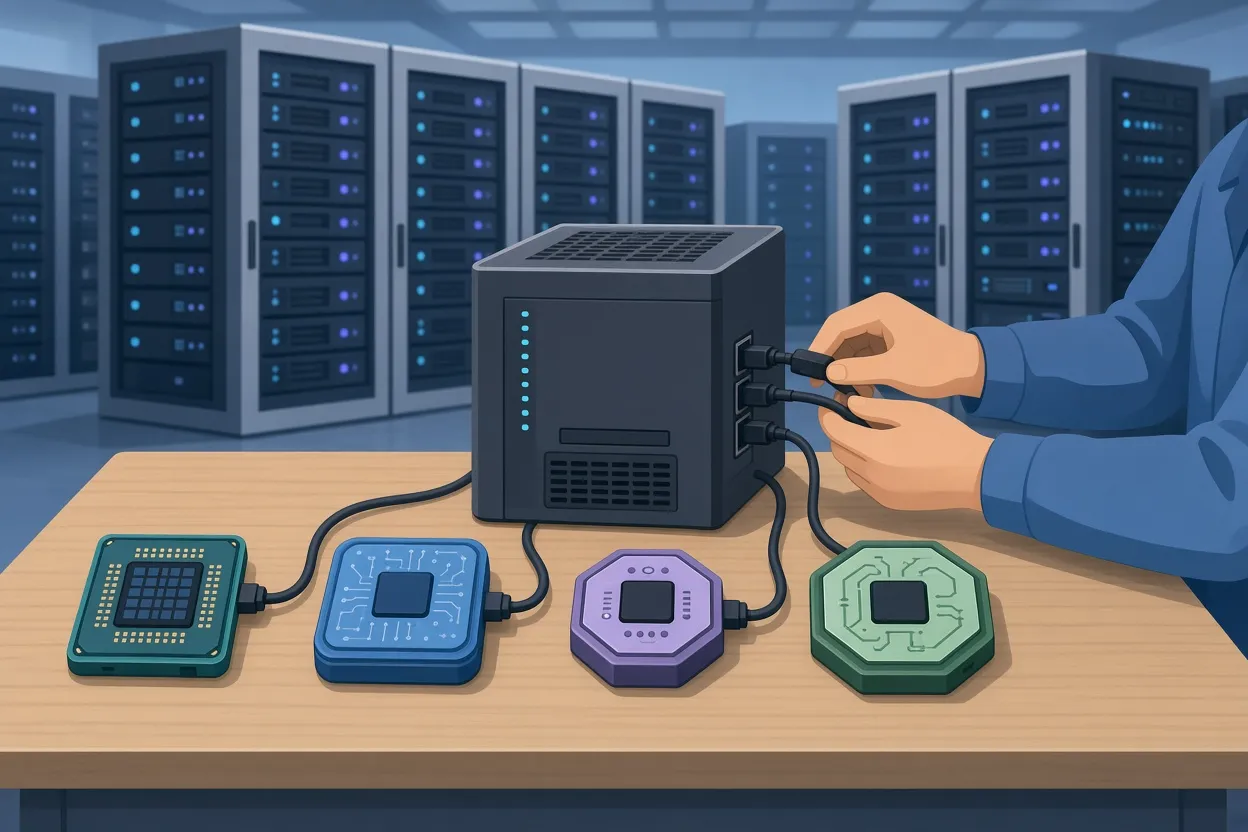
▲ Multi-silicon strategy across chip vendors
The core explanation the investor offers for the cost curve is Anthropic's multi-silicon approach. Rather than depending on NVIDIA GPUs alone, the company trains and runs Claude models across AWS Trainium, Amazon's custom AI accelerator, Google's TPUs (Tensor Processing Units), and AMD chips, alongside NVIDIA hardware. This has been part of the company's architecture from the beginning rather than a later retrofit.
Two benefits follow. The first is commercial: a lab that can shift workloads between chip families and cloud providers negotiates from a stronger position when it buys hardware or secures cloud capacity, because no single supplier holds leverage over it. The second is operational flexibility, since the model stack is not locked to one vendor's roadmap.
The compute multiplier and Claude's role in it
The Baillie Gifford investor also points to what he calls the compute multiplier effect. The idea is that each unit of compute spent on research and inference (the process of running a trained model to produce answers) yields progressively more effective intelligence over time, as the lab finds algorithmic and engineering optimizations that squeeze more capability out of the same hardware.
The development he singles out as most significant is that Claude itself now helps build these optimizations. Anthropic's engineers use the model to develop and refine the efficiency techniques that improve the multiplier. He describes this as the early stage of recursive self-improvement, a loop in which an AI system contributes to improving the next version of itself, and he suggests it could prove one of the largest breakthroughs in the field. That is a forward-looking judgment rather than a measured result, but it is a notable claim coming from an investor explaining why margins have moved.
Governance built to resist the quarter
▲ Founder voting control amid market pressure
Anthropic is organized as a Public Benefit Corporation, a corporate form that obliges the board to weigh a stated public mission alongside shareholder returns. The S-1 also shows the founders retaining 50.1 percent of voting power after the listing, a dual-class arrangement in which the founders' shares carry more votes than those sold to the public.
The investor's position is that any atypical voting structure should make investors demand a convincing rationale, and that Anthropic has one. His argument runs as follows:
- Frontier AI models carry capabilities and societal risks without precedent, so the company building them needs governance that can resist pressure to sacrifice long-term safety for near-term financial gains.
- Anthropic has already shown it will accept short-term commercial sacrifices to make its models safer and more resilient.
- A conventional public-market voting structure could expose the company to activist shareholders pushing for faster, less careful scaling.
- Founder control therefore aligns with long-term value creation rather than working against it.
In this reading, the governance structure is not a concession investors tolerate but a feature that protects the asset they are buying. Anthropic plans to list on the Nasdaq under the ticker ANT, with JPMorgan Chase leading the IPO, and marketing to investors is expected to begin as soon as the week of November 9.
Enterprise adoption: large numbers, small share
The prospectus reports that the number of enterprise customers spending more than $100,000 a year with Anthropic grew from 950 to 1,200. Yet the same document notes that Anthropic's revenue represents less than 0.1 percent of total corporate spending among its Fortune 500 clients. One way to read that gap is as a warning that penetration remains strikingly low relative to the valuation expectations attached to the offering.
The Baillie Gifford executive reads it the other way. He borrows Jeff Bezos's long-running "Day One" framing from Amazon's annual shareholder letters to argue that AI adoption is at the very beginning of a cycle that will play out over decades, not years. He draws parallels to Moore's Law, whose foundations date to the 1940s and 1950s, to the roughly three-decade evolution of the commercial internet, and to the spread of mobile computing. Judging AI infrastructure on an annual timescale, in his view, misreads how platform transitions unfold.
Where usage is spreading
Software engineering was the first area to adopt large language models at scale, which the investor attributes to developers' natural affinity for the tools. He now sees early expansion into legal work, cybersecurity, healthcare, and financial services. The filing's risk factors include competition from narrow, domain-specific models built for a single industry. He accepts that open-source and specialist models will serve many application layers, but he contends that frontier labs building general-purpose models will capture the lion's share of the economic value in the ecosystem. This is a contested question, and the filing itself lists specialist competition as a risk.
How a private backer prepares for a listing
Baillie Gifford's private portfolio includes Anthropic alongside Databricks, Stripe, Kalshi, Anduril, and Revolut, so a large IPO is a scenario the firm has organized around. The head of private companies describes an investment floor in Edinburgh where the private companies team sits directly beside the public equity teams, including North American Equities and Long Term Global Growth. Some client strategies have mandates that allow them to keep shares after an IPO as long-term public holdings, while others rebalance. The private team's main job, as he puts it, is to build multi-year relationships with company executives so that public fund managers can make fully informed allocation decisions when the company lists.
What to take from the filing
The S-1 reframes Anthropic's economics from a story about losses to a story about leverage: compute costs have fallen from 1056 percent of revenue in 2023 to 55 percent in the first half of 2026, driven by a hardware strategy spanning AWS Trainium, Google TPUs, AMD chips, and NVIDIA GPUs, and by Claude's growing contribution to its own efficiency. The 50.1 percent founder voting control and Public Benefit Corporation structure are presented by an early backer as safeguards that let the company scale safely without bending to quarterly pressure.
For readers assessing the company or the sector, three practical lessons emerge from this account. Organizations building AI infrastructure should consider spreading workloads across multiple chip families to limit vendor lock-in and margin strain. Investors weighing frontier AI companies should ask whether a dual-class structure has a specific rationale tied to the risks of the technology, rather than rejecting or accepting it by default. And anyone judging adoption should look at penetration figures such as the sub-0.1 percent share of Fortune 500 spend and decide for themselves whether that signals a ceiling or a starting line. Nothing here is a recommendation to buy or sell shares; it is a description of how one long-term holder reads the numbers.


