JPMorgan Chase has drawn a firm line on AI agents, the software assistants that act on a person’s behalf. On the bank’s third-quarter 2026 earnings call on October 13, CEO Jamie Dimon said JPMorgan will not let outside agents sign in to customer accounts using customers’ own credentials. In practice, an agent built by another company cannot move money or pay bills from a Chase account. Read-only links that only view account data still work. As AI agents begin to handle payments and transfers, the decision shows how a major bank plans to keep control of its customers’ money.
A question about deposits walking out the door
The issue came up when an analyst pressed the bank’s leadership on what AI is actually worth to JPMorgan. He noted that the bank had ranked well in a recent poll on AI in banking, yet asked where the benefits show up in its results. He also cited earlier estimates that JPMorgan had spent about $2 billion on AI and gained roughly $2 billion in benefits, and asked for newer figures.
His sharper concern was about deposits. If autonomous AI agents start shifting customers’ money out of JPMorgan, how does the bank respond? And how does it protect its core value to customers, their trust and their privacy once agents are the ones managing personal finances?
That worry may be closer to reality than it sounds. Asset tokenization, which converts assets such as deposits into a digital form, could let AI agents handle money safely and within the rules. If so, automated deposit transfers would become practical.
The CFO’s view: chasing yield is an old fight
Chief Financial Officer Jeremy Barnum framed the threat as familiar. JPMorgan’s priority, he said, is to secure its place as customers’ primary bank, not to fight for every extra dollar that moves around in search of a higher rate.
He acknowledged that pressure from yield-seeking customers and fintech challengers is real. But he described it as a long-running feature of banking rather than something new. Fintech and technology companies keep rolling out new digital experiences, and JPMorgan has watched that competition for years and works to match what the leading platforms offer.
In Barnum’s framing, personal AI agents are where two existing trends meet: digital user experience and the hunt for yield. The bank is not complacent, he said, but keeping up with technology that customers want is already part of its everyday work.
Dimon’s line: agents are tools, outside agents stay out
Dimon went further and set out the bank’s position plainly.
- JPMorgan builds its own agents. The bank uses internal AI agents to work more efficiently and to improve the customer experience.
- Agents themselves are neutral. Dimon said the bank is neither for nor against AI agents. They are tools.
- Security comes first. He warned about rogue agents, meaning bots that operate outside anyone’s control. Thousands of unvetted bots interacting with financial systems could put customer accounts at risk.
- Logins carry liability. When a customer hands login credentials to an outside agent, responsibility for what happens shifts in ways the customer may not fully understand.
His conclusion was direct. Clients may want agents, but JPMorgan will not let third-party AI agents into its systems.
What is blocked and what still works
A fintech analyst who reviewed the policy laid out the details. Third-party agents, including Meta’s Muse, cannot log in to JPMorgan customer accounts to move money or pay bills. Read-only aggregation, in which a service such as Plaid pulls account data without the power to act on it, remains available.
| Type of access | What it can do | JPMorgan’s stance |
|---|---|---|
| Outside agent using customer login | Move money, pay bills | Blocked |
| Read-only aggregation through Plaid | View account data | Allowed |
| Smart Cash, the bank’s own agent | Move money between a customer’s Chase accounts | In pilot |
The key distinction is between visibility and agency. A read-only connection lets an agent see account data, but it cannot execute a payment or a transfer. Today, AI financial tools depend mainly on read-only aggregators like Plaid rather than on logging in to carry out transactions themselves.
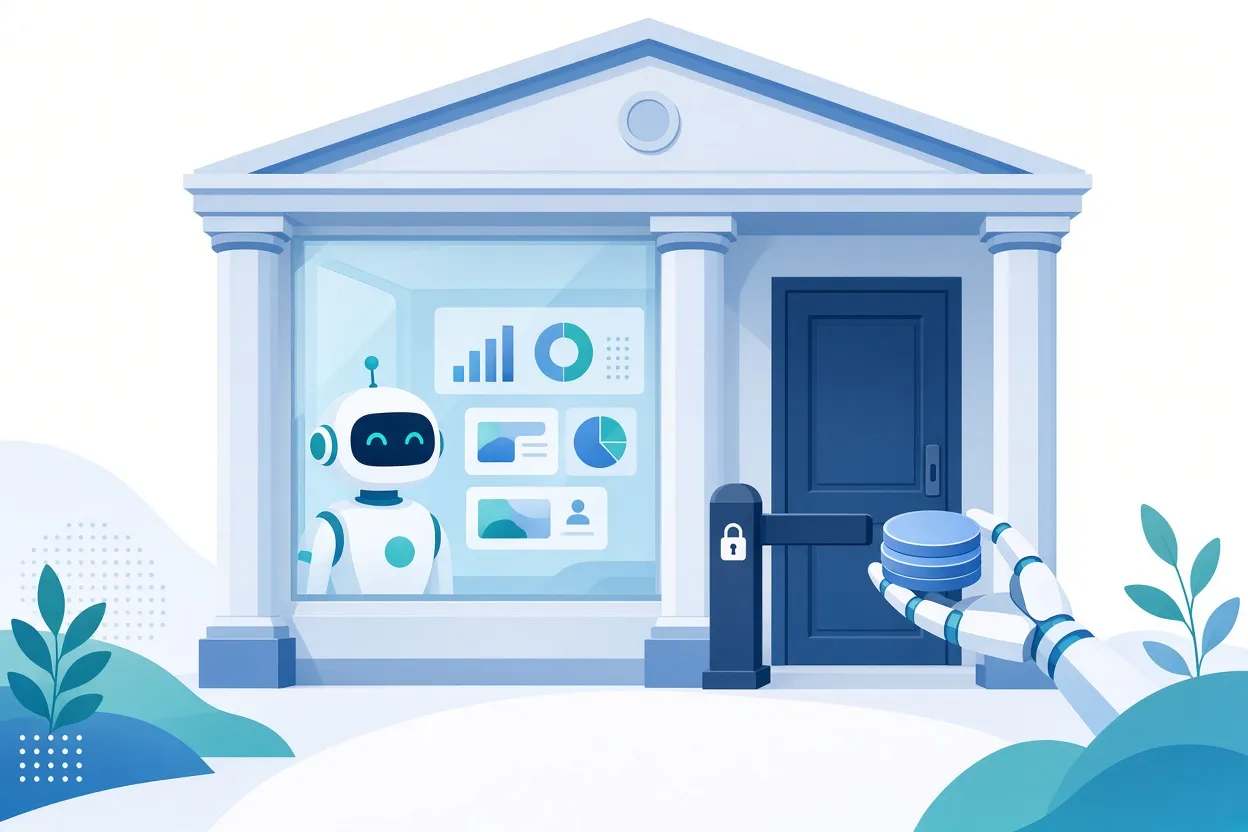
▲ Read-only access versus the power to move money
Why the walls make business sense
Security is only part of the story. Picture an AI financial agent with full account access that spots a better interest rate at another institution. It could simply urge the customer to move their balance out of Chase. Keeping outside agents out also keeps that kind of automated deposit flight in check. Seen this way, JPMorgan appears to be building a walled garden, a closed system in which the platform decides who gets in and what they can do.
The bank is not rejecting agents outright. It is testing its own tool, Smart Cash, which automatically moves a customer’s money between their existing Chase accounts to earn a better yield. Customers get the convenience of an agent managing their cash, while the money stays inside the bank.
JPMorgan is not alone in this approach. Amazon blocked Meta’s Muse after objecting to automated logins into customer accounts, pointing to its terms on third parties using customer credentials. The pattern suggests that large companies and financial institutions will block outside bots first and settle the regulatory and technical terms later.
▲ Deposits kept inside the bank’s walled garden
Can the walls hold?
The bigger open question is whether closed systems can keep outside AI out for good. Friction between banks and open AI agents looks likely to grow, and 2027 could be a turning point as agent-driven finance expands. Established financial institutions will probably keep choosing self-protection by default over open access for customers.
Walls may slow the shift without stopping it. Over time, open blockchain-based payment systems could become the foundation that lets agents move money without passing through traditional bank gates. Either way, the transition is unlikely to be smooth, and it could bring significant market volatility.
What to do now
JPMorgan’s message is that AI agents are welcome only inside its own walls. Outside agents get, at most, a read-only view of your accounts, while moving money is reserved for the bank’s own tools. A few practical steps follow from that.
- If you use an AI money tool: Check whether it relies on read-only access or asks for your bank login. Handing your credentials to an outside agent can shift liability in ways that are easy to miss.
- If you build one: Assume that big-bank accounts will be read-only for now, and design features around viewing data rather than moving it. Expect banks to block first and negotiate terms later.
- Watch the banks’ own agents: Pilots such as Smart Cash show how established institutions plan to hold on to deposits while still offering automation.
- Follow earnings calls: Bank leaders’ comments on AI agents offer an early read on where access policies are heading.